

Freshly back from Medici LA. The mood: Aesop’s tortoise. AI has captured the narrative-driven capital, with overindexing across both diversified and AI-focused funds, but nobody was betting against blockchain. As one allocator put it: “Sometimes it is good to be boring and grow steadily into a strong industry.”
That’s the issue this month. While the headlights point at who controls AI (Altman’s grip on OpenAI, China’s closed-source pivot, social media’s algorithmic freak show), the money infrastructure of the internet is winning. In 2025, real-world stablecoin payments doubled to $400 billion (60% B2B) while Bitcoin fell 50% from its peak. Mercado Libre and Nubank are embedding dollar-backed stablecoins inside the apps 200 million Latin Americans already use. None of it made the front page, but it adds up to the most significant money-layer shift in 25 years.
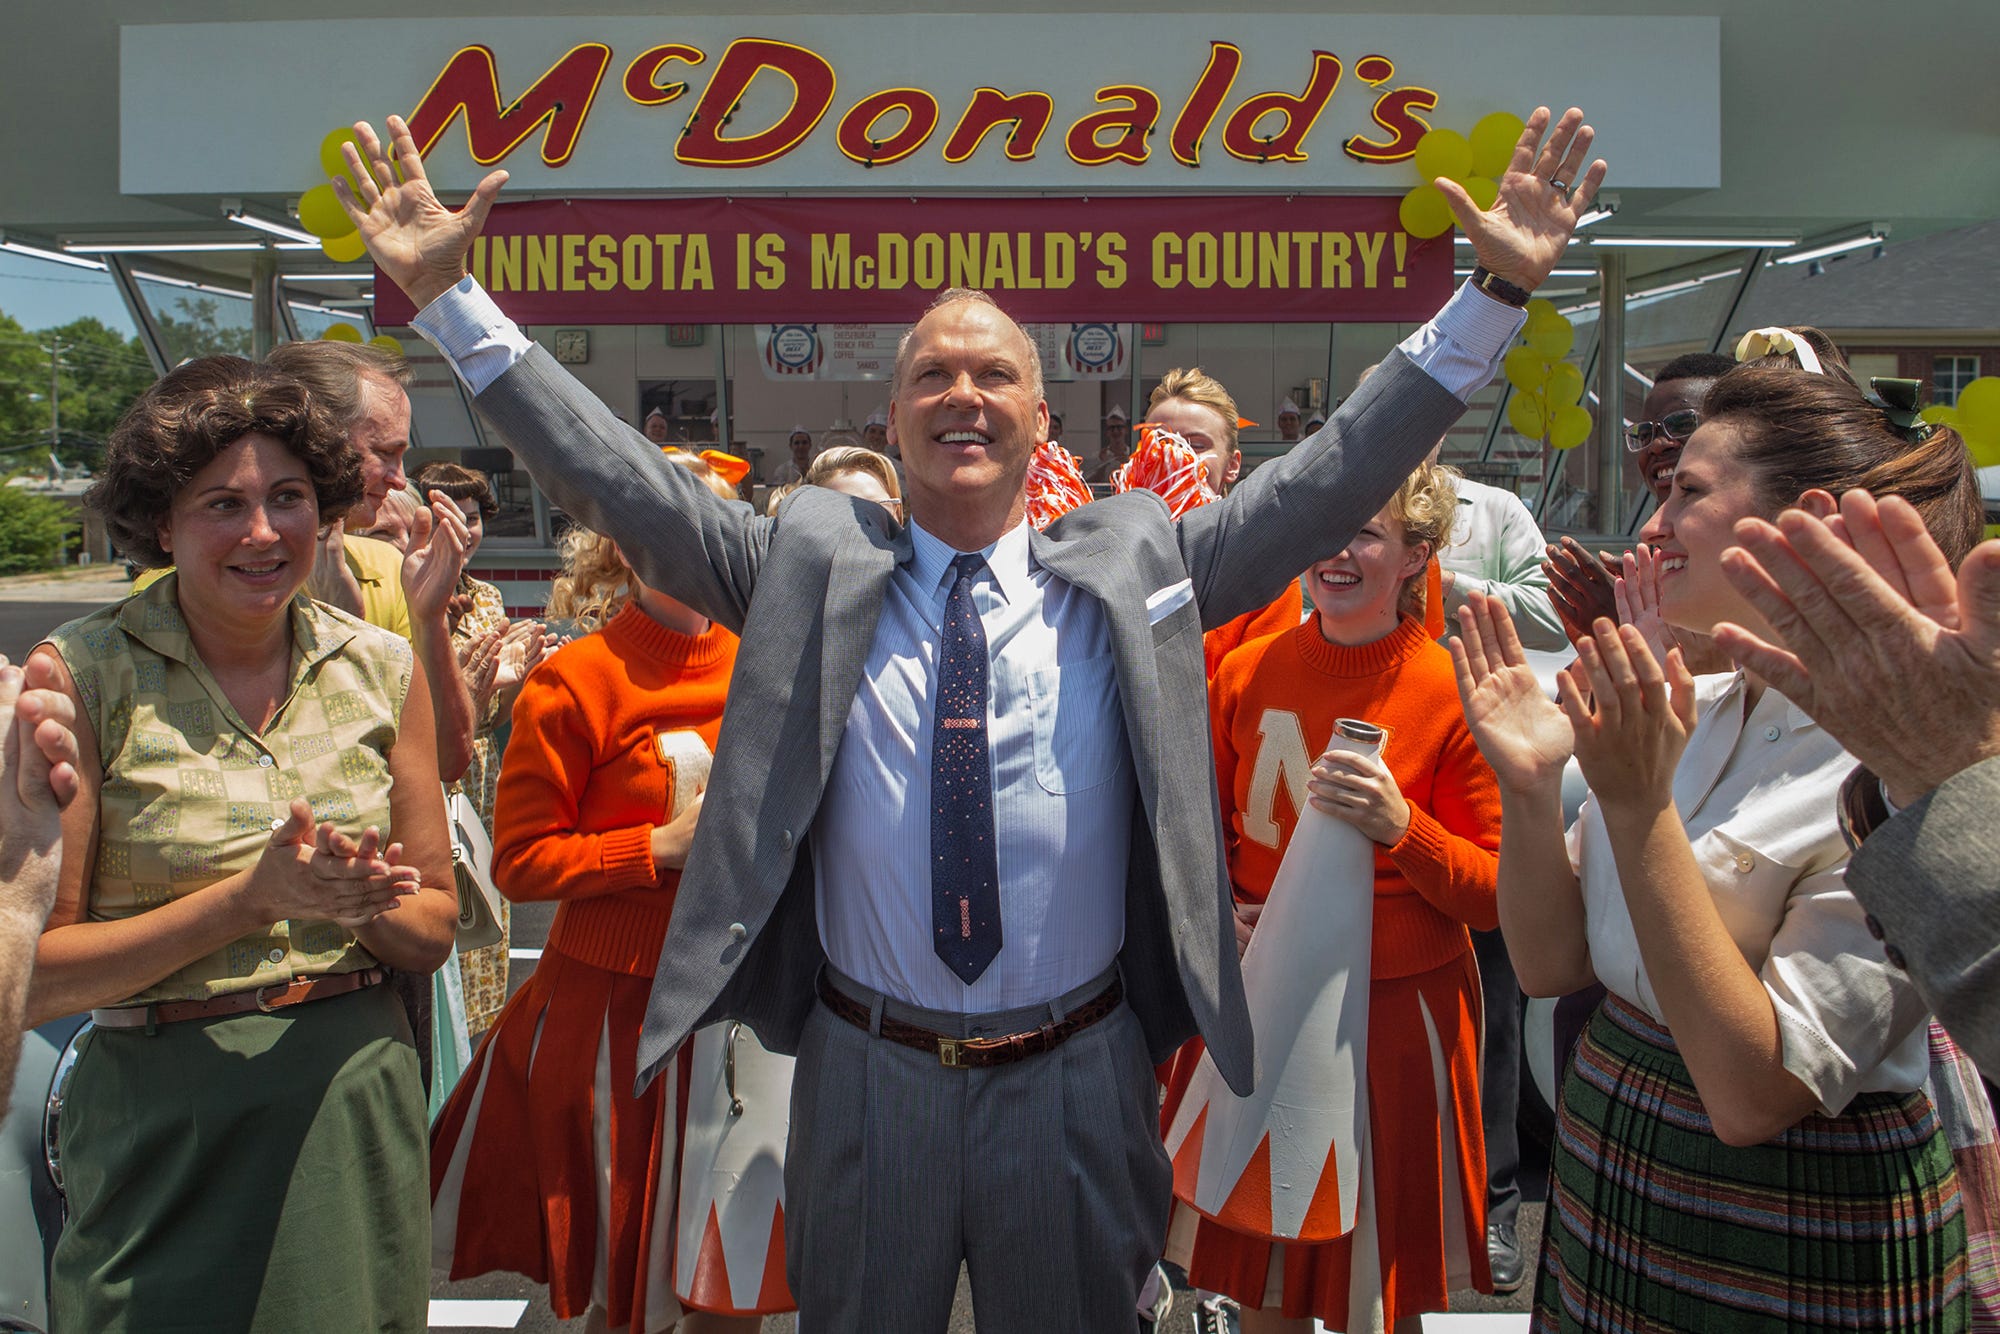
In The Founder, Ray Kroc spends most of the movie thinking he’s in the burger business, until his financial advisor Harry Sonneborn pulls him aside. ‘You’re not in the burger business,’ Sonneborn tells him. ‘You’re in the real estate business.’ The visible product was the cover story, but what he was building underneath was the actual prize. That’s exactly where stablecoins are.
What happens when the new rails finish getting built: what AI agents will do with them, why drones regulatory forcing function for blockchain-anchored airspace, how Stripe is quietly absorbing stablecoin settlement into the checkout people already use, and why a Bessemer atlas might be the most important article of the year.
Convergence is brought to you by The Medici Network LLC (”Medici”)
Integrations We Want To See 🔮
Now that we own our data, here are some things we’ll do with it
Sparks ✨
Quick, curated Web2 and Web3 insights you need to know
#1 Should we give AI a bank account?
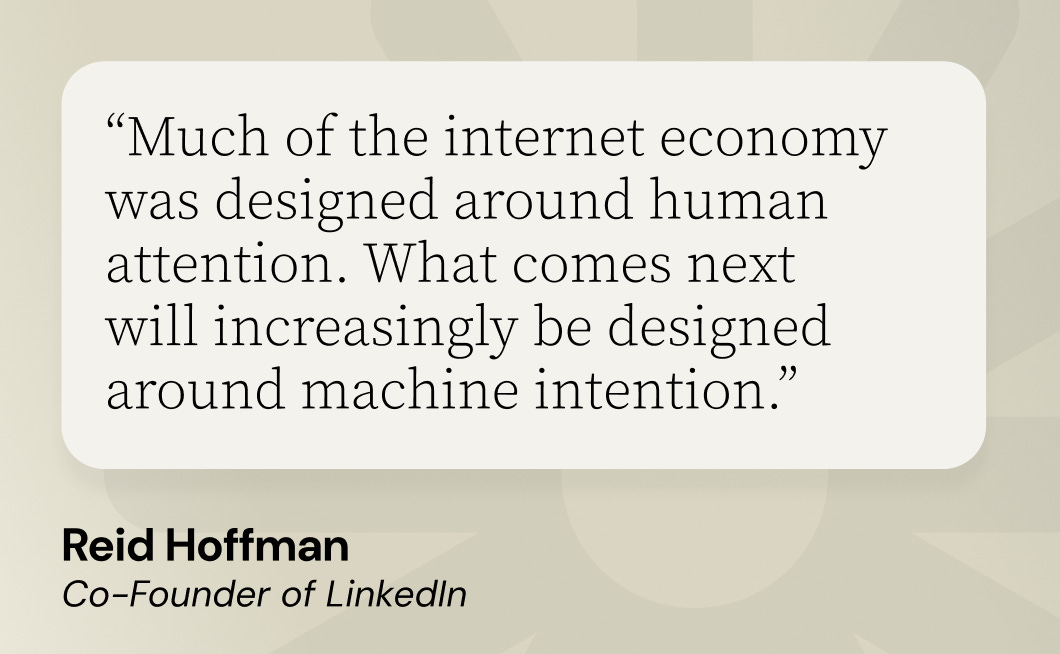
Author: Reid Hoffman (Co-Founder of LinkedIn, Partner at Greylock)

TLDR:
Hoffman argues that AI agents transacting on the internet need their own bank accounts. The card networks we built for human buyers were never going to work for an agent that doesn’t sleep and doesn’t have a CVV to type
The current payment stack is a friction machine. Days-long settlement, %-based interchange, and one-human-at-a-time KYC don’t survive contact with an agent at machine speed
His fix: self-custodial wallets and stablecoin-denominated accounts, so agents can pay each other directly with no human in the loop
Our Takeaway:
We think builders should take this as the green light: Catena Labs (Sean Neville, $18M from a16z), Skyfire (out of beta on Coinbase Ventures money), and Stripe + Paradigm’s Tempo mainnet all went live in the last six months. Coinbase’s x402 protocol already crossed 144 million transactions
Agent-to-agent commerce is the killer stablecoin use case, and it’ll get there long before consumer remittance does. An agent buying compute at three in the morning doesn’t need a dollar-stable narrative; it needs settlement that doesn’t wait for a sleeping human to type a CVV
Watch the issuing banks, not the networks: JPMorgan has been the #1 commercial card issuer on both Visa and Mastercard rails for four consecutive years and just printed $5.1B in quarterly Payments revenue, while Visa collects roughly 13 cents per $100. A five percent migration of B2B card volume to agent-mediated stablecoin settlement by 2027 hits JPM’s balance sheet, not Visa’s
#2 Fortune Op-Ed: Why the key to American drone dominance lies with blockchain
Author: Fortune, Mike Horton (Co-Founder of HYFIX, GEODNET) and Adam Winnick (Co-Founder of Finality Capital, Founder of The Medici Network)

TLDR:
DJI still ships 80% of the world’s commercial drones, which means the firmware, cloud, and geofencing logic securing American airspace is built in Shenzhen, a national security exposure the recent US ban on DJI imports surfaced but didn’t fix
Swapping DJI for one closed American vendor just relocates the vulnerability. The only durable fix is a neutral trust layer where geofence boundaries, drone authentication, GNSS correction data, and Remote ID logs live as signed, on-chain data, not buried inside some other vendor’s database
They name names: Solana, Sui, Base, and Monad as the chains fast enough to handle real-time airspace coordination, and they want federal agencies to certify decentralized Positioning, Navigation, and Timing (PNT) infrastructure where private operators run reference stations and earn tokenized rewards
Our Takeaway:
The vendor-swap trap generalizes way past drones, and Boeing just paid $8.3B to learn it: after twenty years of trying to fix supplier-controlled fuselage quality by managing Spirit AeroSystems better, the 737 MAX crisis forced them to reacquire Spirit outright (closed Dec 2025). The same pattern plays out replacing OpenAI with Anthropic or DJI with Skydio: any domain where “we don’t control the vendor” is the strategic problem can only be solved by architectures that don’t need a vendor at all
The real story is the economics: token rewards turn any private operator into a node, and GEODNET has used those rails to deploy 21K+ GNSS reference stations across 145 countries in under four years (versus NOAA’s National CORS network, which took 25 years of federal procurement to reach ~2,000 stations). Same playbook unlocks rural broadband, weather sensing, mesh comms, and EV-charging telemetry
The DJI ban is to blockchain-anchored airspace what the GENIUS Act was to stablecoins: the regulatory forcing function nobody saw coming. The DOD will adopt fast and the FAA (whose entire culture is built around certifying specific vendors) won’t, so the durable moat belongs to whoever builds the FAA-blessed pathway for an open, decentralized airspace standard
#3 Stripe Is Trying to Make Crypto Disappear
Author: James Smith (Head of Ecoystem Development at Ethereum Foundation, Research at Enterprise Onchain)
TLDR:
James argues Stripe isn’t competing with the on-chain world. It’s burying it inside enterprise payment infrastructure so the customer never has to say “wallet, gas, bridge, validator, or chain.”
The strategy is to assemble the seven gates of payments under one roof: Licensing, Custody, FX, and Issuance (via the Bridge acquisition), Wallets (via Privy), Settlement (via Stripe’s new L1, Tempo, with stablecoin-denominated gas so merchants never hold a volatile asset), and Acquiring (already native)
The kill-shot framing: “Stripe doesn’t need to win the protocol war. It needs the winning protocol to terminate inside Stripe’s balance sheet.”
Our Takeaway:
James reads Stripe’s stack as a kill-shot, but good products always breed hate: Facebook was called a parasite, Tesla a fraud, Apple a thief, all from inside the industries they were catalyzing. Stripe absorbing stablecoin settlement is the same pattern: a Web2 incumbent bringing on-chain rails to consumer-scale distribution, and the addressable market explodes when it does
The disappearance isn’t a loss; it’s the win condition. When stablecoin rails vanish into Stripe’s checkout the way TCP/IP vanished into “the internet,” most users will never know they’re transacting on-chain, and that’s exactly what infrastructure looks like when it’s won
As Stripe absorbs the settlement layer, the next billion-dollar opportunity moves up the stack: Tempo just raised $500M at a a $5B Series A, Mastercard bought BVNK for up to $1.8B the same month, and the agent-payment platforms (Catena, Skyfire) are still pre-Series-A. As the infrastructure war is ending, the application war is beginning
The 3-2-1 🔍
Featured insight breaking down a major story or trend that matters
Stablecoins: From DeFi Primitive to Global Financial Infrastructure
Author: Bessemer Venture Partners
TLDR:
Bessemer’s April atlas is the institutional grade-stamp on a thesis that’s been forming for two years: stablecoins are no longer a digital-assets product, and they’re no longer adjacent to anything. They have become global financial infrastructure. The supply of fiat-backed stablecoins reached $273 billion in March 2026, a forty-fold expansion from $6.8 billion five years ago. Total transaction volume hit $10.9 trillion in 2025, putting stablecoins within striking distance of Visa’s $14.2 trillion. Real-world payments specifically (stripping out trading and treasury flows) doubled to $400 billion, with 60% of that volume coming from B2B.
The clearest signal that the asset class has crossed into real infrastructure is the decoupling. Bitcoin fell roughly 50% from its 2025 peak; stablecoin payment volume accelerated through the same window. The two categories are no longer correlated. Whatever is driving stablecoin adoption has nothing to do with speculative appetite for digital assets.
Bessemer credits two unlocks: the GENIUS Act, which gives U.S. institutional treasuries the first federal framework for stablecoin issuance, and the on-and-off-ramp stack (Bridge, BVNK, Conduit, Felix Pago, Rain, Polygon) finally hitting enterprise-grade reliability. Stripe’s $1.1B acquisition of Bridge was the moment that told strategic buyers to stop waiting. The atlas’s pitch to the venture community is essentially that the rails are done; the next billion-dollar companies are the products that route over them.
Our Takeaway:
The public markets still treat stablecoins as a digital-assets story. Instead, they are the most important payments infrastructure shift since the SWIFT network went live in 1977; the institutions that price the world’s financial assets have not yet repriced what that means. Bessemer’s atlas matters because it’s the first document from a big web2 venture firm that says this in plain language.
The Web2 problem this solves isn’t a doomsayer omen, so it’s not that fun: correspondent banking is a 40-year-old kludge that everyone in payments knows is broken and nobody can replace alone. Cross-border B2B transactions move through chains of three to five intermediary banks, each holding pre-funded float in destination currencies, each charging spread, each settling on different schedules in different time zones. The end-to-end cost is somewhere between 2-7% percent depending on the corridor, and the settlement time is 2-5 business days. That entire structure existed because there was no alternative until now.
The on-chain answer is what Bessemer highlights. Self-custodial wallets remove the need for pre-funded float in destination countries. 24-hour settlement removes the time-zone arbitrage. Programmable rails let treasuries automate flows that previously required a human at each end. But, the numbers in the atlas are not the story. The story is what they imply: a generation of fintech infrastructure built on top of the old correspondent banking system is being quietly disintermediated by a layer of dollar-backed tokens that didn’t exist when those companies were founded.
Victor Cioffi at Nora put the historical arc cleanly when he was writing about Brazil earlier this year. The first financial revolution was credit unions, a parallel banking system built when incumbents wouldn’t serve a continent. The second was Nubank, which changed the consumer interface and forced the market to ship faster, prettier, and more transparent. The third (happening now, across emerging markets first and the rest of the world fast behind) is a rails reset powered by stablecoins. Cioffi’s framing says this isn’t a trend but rather a confirmation that the third revolution has already started.
The smart skeptic asks whether central bank digital currencies displace this layer before it scales. The data says the opposite. Of 134 countries exploring CBDCs, only three have launched a retail version, and the largest (China’s e-CNY) has done 3.48 billion transactions without denting the cross-border flows running through Tether and Circle. The functional split: CBDCs are surveillance-optimized rails for sovereign control inside a jurisdiction; stablecoins are speed-optimized rails for permissionless settlement across them. Both will exist. The CBDC threat actually sharpens BVP thesis.
The 18-month vision runs in two directions. Institutionally, the trajectory is anchored: monthly B2B volume went from under $100 million in early 2023 to over $3 billion by mid-2025, and from today’s $240 billion baseline, capturing 1-3% of the $150 trillion global cross-border B2B market by end of 2027 is on-trajectory (Juniper Research projects $5 trillion by 2035). On the consumer side (Mercado Libre, Nubank, Rain-powered cards, plus the agent-to-agent commerce Hoffman is asking for), the volume will be larger but invisible to the user. That invisibility is the win condition: when the rails disappear into the apps people already use, the migration is complete.
Power Quote:
At its core, a stablecoin is like a digital version of a dollar bill that lives on the internet, that you can send to anyone in the world instantly, at any time, without going through a bank.
What We’re Downloading 🎧
Podcasts, interviews, discussions, and research reports that are influencing our thinking
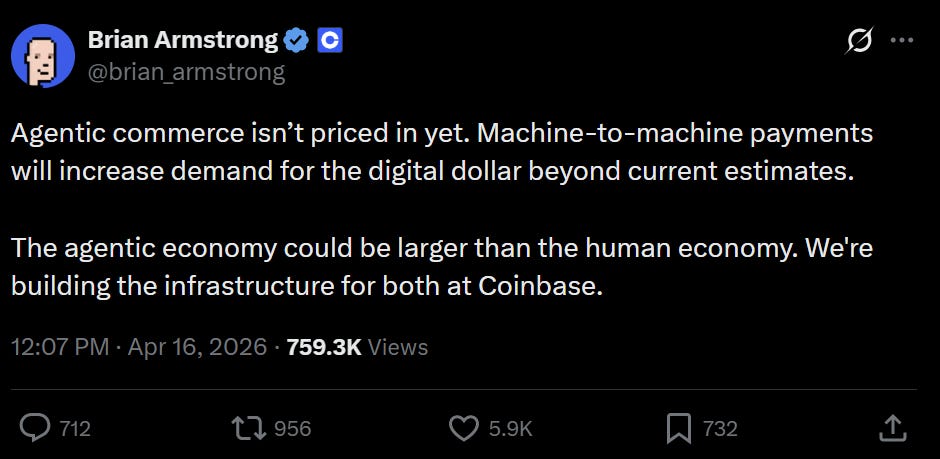
Tweet of the Month 🐦
Key takeaways and perspectives from X
Brian Armstrong (CEO / Founder of Coinbase)
Meme of the Month 📸
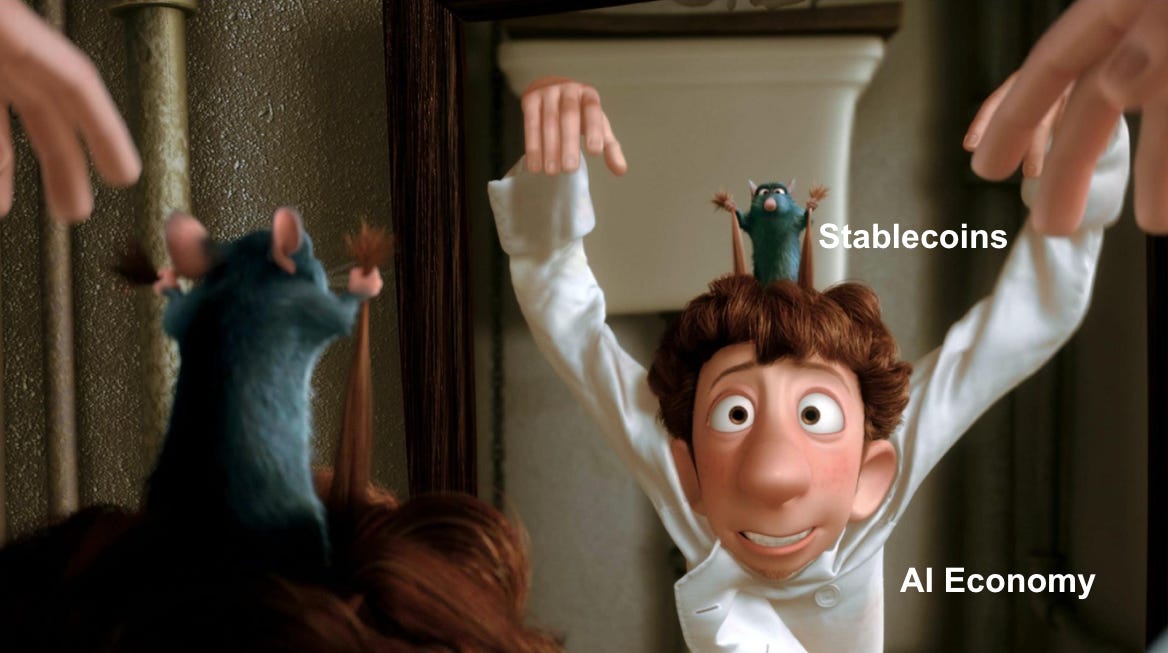
Send us your memes for a chance to be featured: hello@321converge.com
See you next month,
Nick Tang
X: 0xtangelo
Kris Jenk
X: 0xjinkys
Suggest an article or blog post for next month’s Convergence here.